
No. 275 – Money in the bank could cost you more in tax
Question
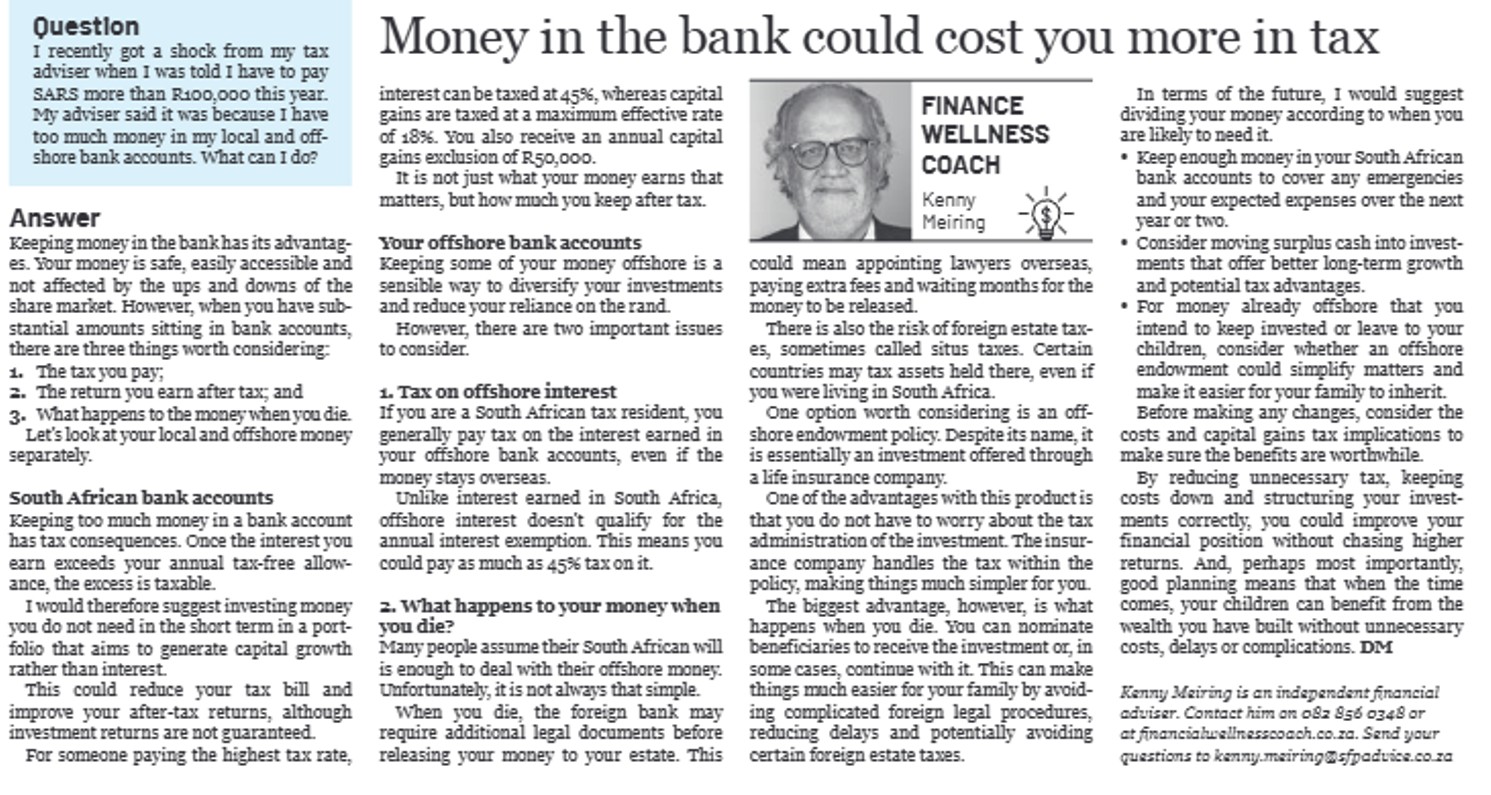
I recently got a shock from my tax advisor and was told I have to pay SARS over R100 000 this year. My advisor said it was because I have too much money in my local and offshore bank accounts. What can I do?
Answer
Keeping money in the bank has its advantages. Your money is safe, easily accessible and not affected by the ups and downs of the share market.
However, when you have substantial amounts sitting in bank accounts, there are three things worth considering:
- the tax you pay
- the return you earn after tax
- what happens to your money when you die.
Let’s look at your local and offshore money separately.
Your South African bank accounts
Keeping too much money in a bank account has tax consequences. Once the interest you earn exceeds your annual tax-free allowance, the excess is taxable.
I would therefore suggest investing money you do not need in the short term in a portfolio that aims to generate capital growth rather than interest. This could reduce your tax bill and improve your after-tax returns, although investment returns are not guaranteed.
For someone paying the highest tax rate, interest can be taxed at 45%, while capital gains are taxed at a maximum effective rate of 18%. You also receive an annual capital gains exclusion of R50,000.
It is not just what your money earns that matters, but how much you keep after tax.
Your offshore bank accounts: A different set of problems
Keeping some of your money offshore is a sensible way to diversify your investments and reduce your reliance on the rand. However, there are two important issues to consider.
- Tax on offshore interest
If you are a South African tax resident, you generally pay tax on the interest earned in your offshore bank accounts, even if the money stays overseas.
Unlike interest earned in South Africa, offshore interest does not qualify for the annual interest exemption. This means you could pay as much as 45% tax on the interest earned.
- What happens to your money when you die?
Many people assume their South African will is enough to deal with their offshore money. Unfortunately, it is not always that simple.
When you die, the foreign bank may require additional legal documents before releasing your money to your estate. This could mean appointing lawyers overseas, paying extra fees and waiting months for the money to be released.
There is also the risk of foreign estate taxes, sometimes called situs taxes. Certain countries may tax assets held there, even if you were living in South Africa.
One option worth considering is an offshore endowment policy. Despite its name, it is essentially an investment offered through a life insurance company.
One of the advantages with this product is that you do not have to worry about the tax administration of the investment. The insurance company handles the tax within the policy, making things much simpler for you.
The biggest advantage, however, is what happens when you die. You can nominate beneficiaries to receive the investment or, in some cases, continue with it. This can make things much easier for your family by avoiding complicated foreign legal procedures, reducing delays and potentially avoiding certain foreign estate taxes.
Going forward, I would suggest dividing your money according to when you are likely to need it.
- Keep enough money in your South African bank accounts to cover emergencies and expected expenses over the next year or two.
- Consider moving surplus cash into investments that offer better long-term growth and potential tax advantages.
- For money already offshore that you intend to keep invested or leave to your children, consider whether an offshore endowment could simplify matters and make it easier for your family to inherit.
Before making any changes, consider the costs and possible capital gains tax implications to make sure the benefits are worthwhile.
The bottom line is that making your money work harder does not always mean taking more risk. Sometimes it is simply about being smarter with what you already have. By reducing unnecessary tax, keeping costs down and structuring your investments correctly, you could improve your financial position without chasing higher returns.
And perhaps most importantly, good planning means that when the time comes, your children can benefit from the wealth you have built without unnecessary costs, delays or complications.
KENNY MEIRING IS AN INDEPENDENT FINANCIAL ADVISER
Contact him via phone, email or via contact phone on the financialwellnesscoach.co.za website
Read more of our articles on the Daily Maverick website or newspaper weekly!
 adminfwc
No. 276 – Protecting your family finances while freelancing
adminfwc
No. 274 – Weighing up rental income against long-term investment growth
adminfwc
No. 273 – Three effective ways for passing wealth to grandchildren
adminfwc
No. 272 – Plan ahead for business ownership after death
adminfwc
No. 271 – Planning for living and having money left to leave after your death
adminfwc
No. 270 – Making sure that where there is a will, there is clarity, not chaos
adminfwc
No. 269 – Preserving property while treating children fairly
adminfwc
No. 268 – Access bonds can boost emergency savings, but discipline is vital
adminfwc
No. 267 – The case for giving children an early inheritance
adminfwc