
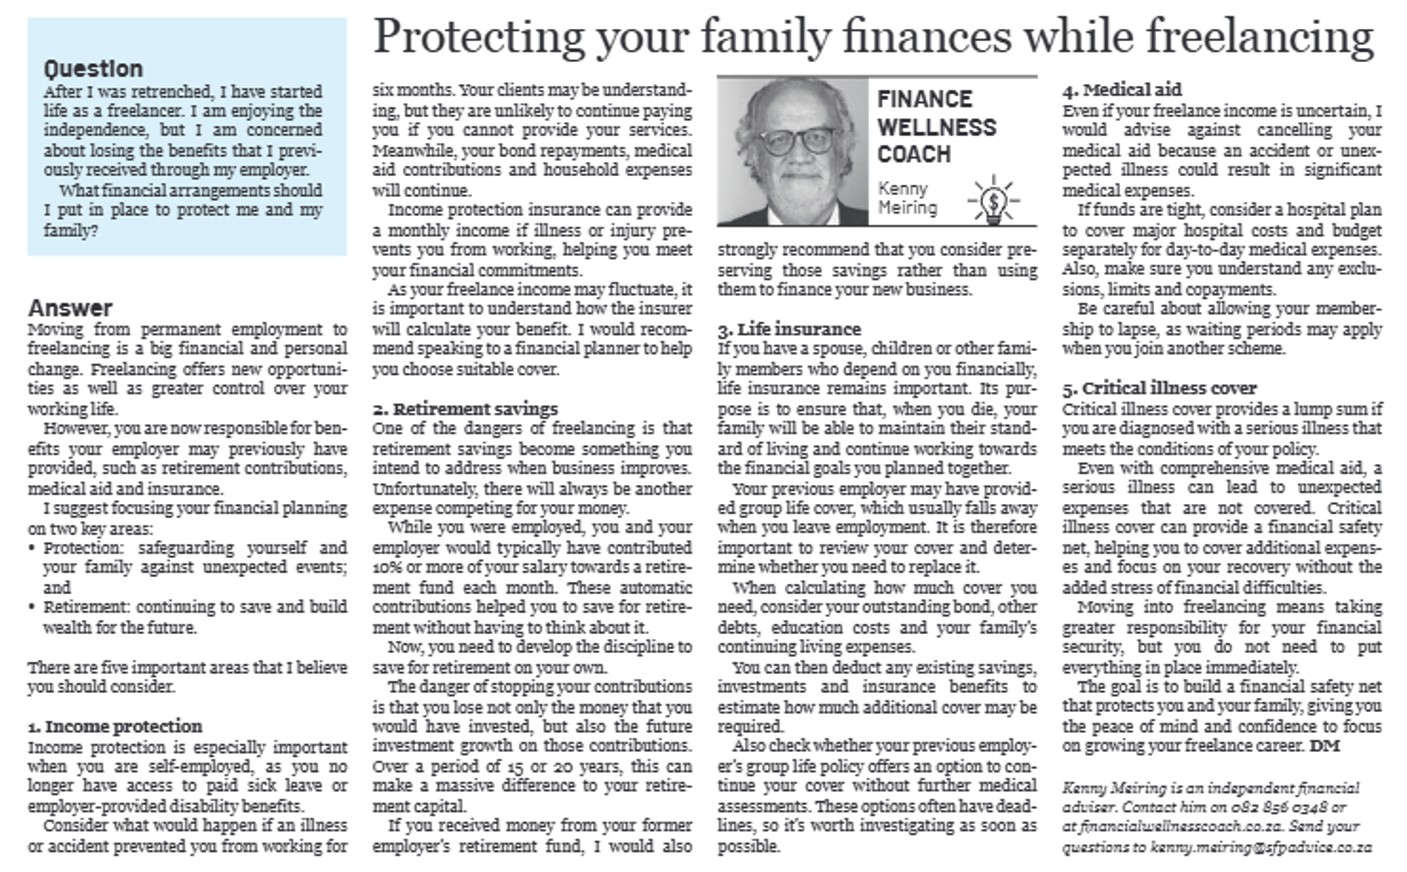
No. 276 – Protecting your family finances while freelancing
Question
After I was retrenched, I have started life as a freelancer. I am enjoying the independence, but I am concerned about losing the benefits that I previously received through my employer. What financial arrangements should I put in place to protect myself and my family?
Answer
Moving from permanent employment to freelancing is a big financial and personal change.
While the decision may not have been entirely yours, freelancing offers new opportunities and greater control over your working life. However, you are now responsible for benefits your employer may previously have provided, such as retirement contributions, medical aid and insurance. It is important to remember that your freelance income is not the same as your previous salary. You need to budget for these benefits, tax and months when your income may be lower.
I suggest focusing your financial planning on two key areas:
- Protection: Safeguarding yourself and your family against unexpected events.
- Retirement: Continuing to save and build wealth for the future.
There are five important areas that I believe you should consider.
- Income protection
Income protection is especially important when you are self-employed, as you no longer have access to paid sick leave or employer-provided disability benefits.
Consider what would happen if an illness or accident prevented you from working for six months. Your clients may be understanding, but they are unlikely to continue paying you if you cannot provide your services. Meanwhile, your bond repayments, medical aid contributions and household expenses will continue. Without an income, you could quickly find yourself relying on your savings.
Income protection insurance can provide a monthly income if illness or injury prevents you from working, helping you meet your financial commitments.
As your freelance income may fluctuate, it is important to understand how the insurer will calculate your benefit. I would recommend speaking to a financial planner to help you choose suitable cover for your needs and budget.
- Retirement savings
One of the dangers of freelancing is that retirement savings become something you intend to address when business improves. Unfortunately, there will always be another expense competing for your money.
While you were employed, you and your employer would typically have contributed 10% or more of your salary towards a retirement fund each month. These automatic contributions helped you save for retirement without having to think about it. Now, you need to develop the discipline to save for retirement on your own.
The danger of stopping your contributions is that you lose not only the money that you would have invested but also the future investment growth on those contributions. Over a period of 15 or 20 years, this can make a massive difference to your retirement capital.
If you received money from your former employer’s retirement fund, I would also strongly recommend that you consider preserving those savings rather than using them to finance your new business. Your retirement capital should ideally remain invested for its original purpose.
- Life insurance
If you have a spouse, children or other family members who depend on you financially, life insurance remains important. Its purpose is to ensure that, should you pass away, your family can maintain their standard of living and continue working towards the financial goals you planned together.
Your previous employer may have provided group life cover, which usually falls away when you leave employment. It is therefore important to review your cover and determine whether you need to replace it.
When calculating how much cover you need, consider your outstanding bond, other debts, education costs and your family’s ongoing living expenses. You can then deduct any existing savings, investments and insurance benefits to estimate how much additional cover may be required.
Also check whether your previous employer’s group life policy offers an option to continue your cover without further medical assessments. These options often have deadlines, so it is worth investigating as soon as possible.
- Medical Aid
Even if your freelance income is uncertain, I would advise against cancelling your medical aid. An unexpected illness or accident could result in significant medical expenses.
If funds are tight, consider a hospital plan to cover major hospital costs, while budgeting separately for day-to-day medical expenses. Also, make sure you understand any exclusions, limits and co-payments.
Be careful about allowing your membership to lapse, as waiting periods may apply when you join another scheme.
- Critical illness cover
Critical illness cover provides a lump sum if you are diagnosed with a serious illness that meets the conditions of your policy.
Even with comprehensive medical aid, a serious illness can lead to unexpected expenses that are not covered. These costs, combined with a possible loss of income, can place significant pressure on your finances.
Critical illness cover can provide a financial safety net, helping you cover additional expenses and focus on your recovery without the added stress of financial difficulties.
Moving into freelancing means taking greater responsibility for your financial security, but you do not need to put everything in place immediately.
The goal is to build a financial safety net that protects you and your family, giving you the peace of mind and confidence to focus on growing your freelance career.
KENNY MEIRING IS AN INDEPENDENT FINANCIAL ADVISER
Contact him via phone, email or via contact phone on the financialwellnesscoach.co.za website
Read more of our articles on the Daily Maverick website or newspaper weekly!
 adminfwc
No. 275 – Money in the bank could cost you more in tax
adminfwc
No. 274 – Weighing up rental income against long-term investment growth
adminfwc
No. 273 – Three effective ways for passing wealth to grandchildren
adminfwc
No. 272 – Plan ahead for business ownership after death
adminfwc
No. 271 – Planning for living and having money left to leave after your death
adminfwc
No. 270 – Making sure that where there is a will, there is clarity, not chaos
adminfwc
No. 269 – Preserving property while treating children fairly
adminfwc
No. 268 – Access bonds can boost emergency savings, but discipline is vital
adminfwc
No. 267 – The case for giving children an early inheritance
adminfwc