
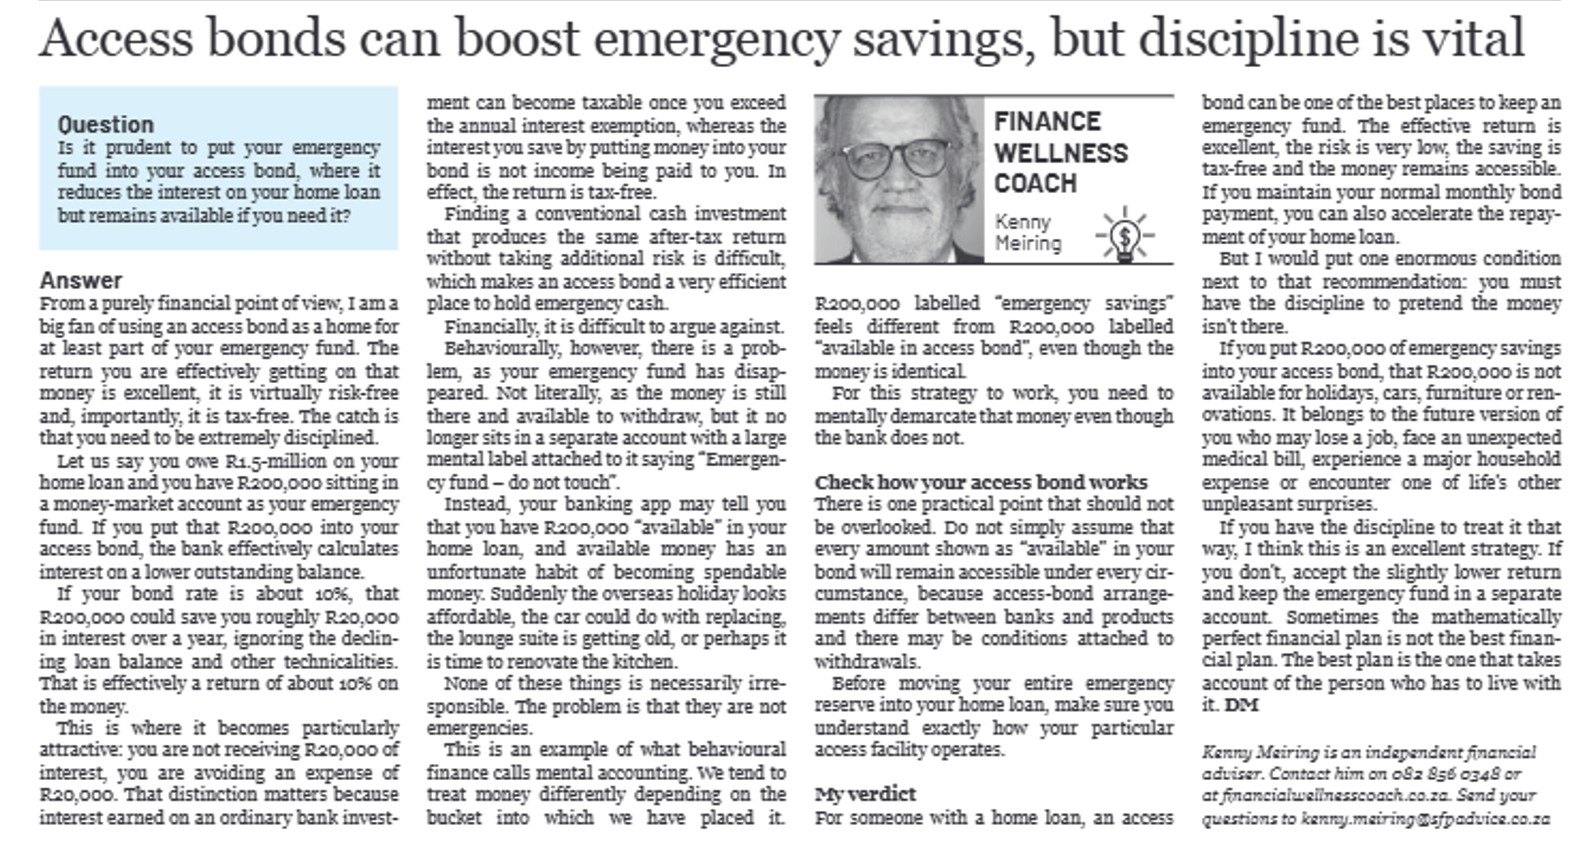
No. 268 – Access bonds can boost emergency savings, but discipline is vital
Question
Is it prudent to put your emergency fund into your access bond, where it reduces the interest on your home loan but remains available if you need it?
Answer
From a purely financial point of view, I am a big fan of using an access bond as a home for at least part of your emergency fund. The return you are effectively getting on that money is excellent, it is virtually risk-free and, importantly, it is tax-free. The catch is that you need to be extremely disciplined.
Let us say you owe R1.5 million on your home loan and you have R200,000 sitting in a money-market account as your emergency fund. If you put that R200,000 into your access bond, the bank effectively calculates interest on a lower outstanding balance. You still owe the money contractually, but while the R200,000 remains in the bond, you are not paying home-loan interest on it.
If your bond rate is around 10%, that R200,000 could save you roughly R20,000 in interest over a year, ignoring the declining loan balance and other technicalities. That is effectively a return of around 10% on the money.
This is where it becomes particularly attractive: you are not receiving R20,000 of interest, you are avoiding an expense of R20,000. That distinction matters because interest earned on an ordinary bank investment can become taxable once you exceed the annual interest exemption, while the interest you save by putting money into your bond is not income being paid to you. In effect, the return is tax-free.
Finding a conventional cash investment that produces the same after-tax return without taking additional risk is difficult, which makes an access bond a very efficient place to hold emergency cash.
Financially, it is difficult to argue against.
Behaviourally, however, there is a problem as your emergency fund has disappeared Not literally. The money is still there and available to withdraw, but it no longer sits in a separate account with a large mental label attached to it saying EMERGENCY FUND – DO NOT TOUCH.
Instead, your banking app may tell you that you have R200,000 “available” in your home loan, and available money has an unfortunate habit of becoming spendable money. Suddenly the overseas holiday looks affordable, the car could do with replacing, the lounge suite is getting old, or perhaps it is time to renovate the kitchen.
None of these things is necessarily irresponsible. The problem is that they are not emergencies.
This is an example of what behavioural finance calls mental accounting. We tend to treat money differently depending on the bucket into which we have placed it. R200,000 labelled “emergency savings” feels different from R200,000 labelled “available in access bond”, even though the money is identical.
For this strategy to work, you need to mentally demarcate that money even though the bank does not.
Check how your access bond works
There is one practical point that should not be overlooked. Do not simply assume that every amount shown as “available” in your bond will remain accessible under every circumstance, because access-bond arrangements differ between banks and products and there may be conditions attached to withdrawals.
Before moving your entire emergency reserve into your home loan, make sure you understand exactly how your particular access facility operates.
My verdict
For someone with a home loan, an access bond can be one of the best places to keep an emergency fund. The effective return is excellent, the risk is very low, the saving is tax-free and the money remains accessible. If you maintain your normal monthly bond payment, you can also accelerate the repayment of your home loan.
But I would put one enormous condition next to that recommendation: you must have the discipline to pretend the money isn’t there.
If you put R200,000 of emergency savings into your access bond, that R200,000 is not available for holidays, cars, furniture or renovations. It belongs to the future version of you who may lose a job, face an unexpected medical bill, experience a major household expense or encounter one of life’s other unpleasant surprises.
If you have the discipline to treat it that way, I think this is an excellent strategy. If you don’t, accept the slightly lower return and keep the emergency fund in a separate account. Sometimes the mathematically perfect financial plan is not the best financial plan. The best plan is the one that takes account of the person who has to live with it.
KENNY MEIRING IS AN INDEPENDENT FINANCIAL ADVISER
Contact him via phone, email or via contact phone on the financialwellnesscoach.co.za website
Read more of our articles on the Daily Maverick website or newspaper weekly!
 adminfwc
No. 272 – Plan ahead for business ownership after death
adminfwc
No. 271 – Planning for living and having money left to leave after your death
adminfwc
No. 270 – Making sure that where there is a will, there is clarity, not chaos
adminfwc
No. 269 – Preserving property while treating children fairly
adminfwc
No. 267 – The case for giving children an early inheritance
adminfwc
No. 266 – Three principles to guide investment decisions
adminfwc
No. 265 – US asset may not be the best bet when it comes to estate planning
adminfwc
No. 264 – Turning property proceeds into a tax-efficient retirement income
adminfwc
No. 263 – How to plan for your pets’ care after your death
adminfwc