
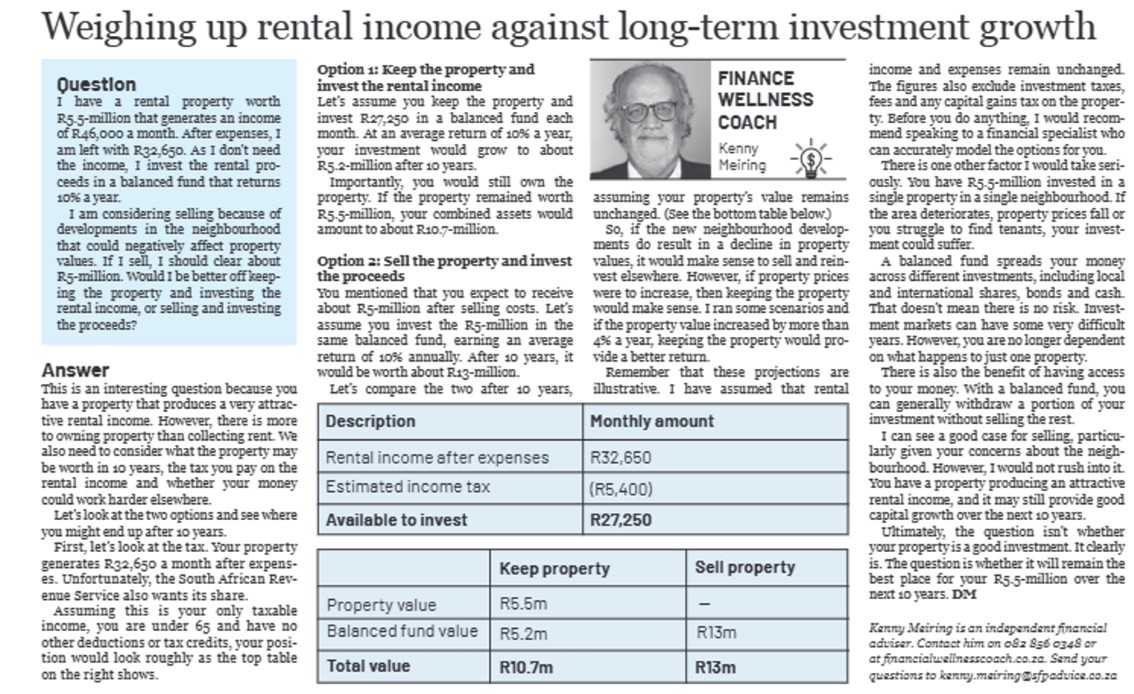
No. 274 – Weighing up rental income against long-term investment growth
Question
I have a rental property worth R5.5 million that generates an income of R46,000 a month. After expenses, I am left with R32,650. As I don’t need the income, I invest the rental proceeds in a balanced fund that returns 10% a year.
I am considering selling because of developments in the neighbourhood that could negatively affect property values. If I sell, I should clear approximately R5 million. Would I be better off keeping the property and investing the rental income, or selling and investing the proceeds?
Answer
This is an interesting question because you have a property that produces a very attractive rental income.
However, there is more to owning property than collecting rent. We also need to consider what the property may be worth in ten years, the tax you pay on the rental income and whether your money could work harder elsewhere.
Let’s look at the two options and see where you might end up after ten years.
First, let’s look at the tax
Your property generates R32,650 a month after expenses, which amounts to R391,800 a year.
Unfortunately, SARS also wants its share. Assuming this is your only taxable income, you are under 65 and have no other deductions or tax credits, your position would look approximately as follows:
|
Description |
Monthly amount |
|
Rental income after expenses |
R32,650 |
|
Estimated income tax |
(R5,400) |
|
Available to invest |
R27,250 |
Option 1: Keep the property and invest the rental income
Let’s assume you keep the property and invest R27 250 into a balanced fund each month. At an average return of 10% a year, your investment would grow to approximately R5.2 million after ten years.
Importantly, you would still own the property. If the property remained worth R5.5 million, your combined assets would amount to approximately R10.7 million.
Option 2: Sell the property and invest the proceeds
You mentioned that you expect to receive approximately R5 million after selling costs. Let’s assume you invest the full R5 million in the same balanced fund, earning an average return of 10% annually. After ten years, your investment would be worth approximately R13 million.
Let’s compare the two after ten years, assuming your property’s value remains unchanged.
|
Keep property |
Sell property |
|
|
Property value |
R5.5m |
— |
|
Balanced fund value |
R5.2m |
R13m |
|
Total value |
R10.7m |
R13m |
So if the new neighbourhood developments do result in a decline in property values, it would make sense to sell and reinvest elsewhere.
However, if property prices were to increase then keeping the property would make sense, I ran some scenarios and if the property value increased by more than 4% a year, keeping the property would provide a better return
Remember that these projections are illustrative. I have assumed that rental income and expenses remain unchanged. The figures also exclude investment taxes, fees and any capital gains tax on the property. Before you do anything, I would recommend speaking to a financial specialist who can accurately model the options for you.
Don’t forget about the risks
There is one other factor that I would take seriously. You currently have R5.5 million invested in a single property, in a single neighbourhood. If the area deteriorates, property prices fall or you struggle to find tenants, your investment could suffer.
A balanced fund spreads your money across different investments, including local and international shares, bonds and cash. That doesn’t mean there is no risk. Investment markets can also have some very difficult years. However, you are no longer dependent on what happens to just one property.
There is also the benefit of having access to your money. If you need R100,000, you cannot sell one bedroom of your house. With a balanced fund, you can generally withdraw a portion of your investment without selling the rest.
I can see a good case for selling, particularly given your concerns about the neighbourhood.
However, I would not rush into it. You have a property producing an attractive rental income, and it may still provide good capital growth over the next ten years.
Ultimately, the question isn’t whether your property is a good investment. It clearly is. The question is whether it will remain the best place for your R5.5 million over the next ten years.
KENNY MEIRING IS AN INDEPENDENT FINANCIAL ADVISER
Contact him via phone, email or via contact phone on the financialwellnesscoach.co.za website
Read more of our articles on the Daily Maverick website or newspaper weekly!
 adminfwc
No. 276 – Protecting your family finances while freelancing
adminfwc
No. 275 – Money in the bank could cost you more in tax
adminfwc
No. 273 – Three effective ways for passing wealth to grandchildren
adminfwc
No. 272 – Plan ahead for business ownership after death
adminfwc
No. 271 – Planning for living and having money left to leave after your death
adminfwc
No. 270 – Making sure that where there is a will, there is clarity, not chaos
adminfwc
No. 269 – Preserving property while treating children fairly
adminfwc
No. 268 – Access bonds can boost emergency savings, but discipline is vital
adminfwc
No. 267 – The case for giving children an early inheritance
adminfwc