
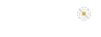
No. 272 – Plan ahead for business ownership after death
Question
My husband owns a business with two partners. If my husband dies what happens to his shares and how do I make sure I receive the value of his share of the business?
Answer
You do not necessarily inherit the shares themselves. What happens will depend on the will and the agreements governing the business
While the business interest may be worth several million rand on paper, it is not necessarily an asset that can simply be sold when the money is needed. In many private businesses there may only be one realistic group of buyers for those shares – the remaining shareholders. You therefore need a structure to ensure that these remaining shareholders give you a fair price for the shares.
This is where a properly structured buy-and-sell agreement can play an important role.
What happens when your husband dies?
Assume, for example, that your husband owns one-third of a business together with two other shareholders. The business is worth R15 million, making his share worth approximately R5 million. If he dies, that R5 million business interest represents a significant asset in his estate, but you may have no involvement in the business and no desire to become involved in running it.
At the same time, the two surviving shareholders may have spent many years building and managing the business alongside your husband. They may not want to find themselves in business with a deceased partner’s spouse who was never involved in the company in the first place.
The practical outcome in many cases is therefore that the surviving shareholders acquire your husband’s shares while his estate receives fair value for them.
In our example, instead of you inheriting a one-third interest in a business that you do not understand or cannot easily sell, your husband’s estate would receive approximately R5 million in cash.
Buy-and-sell
A buy-and-sell agreement is essentially an agreement between business owners setting out what will happen to their interests when a particular event occurs, most commonly the death of one of the shareholders. It can provide that, when one shareholder dies, the surviving shareholders are required to purchase the deceased shareholder’s interest.
This gives both sides certainty.
The surviving shareholders know that they can acquire the shares and continue running the business, while the deceased shareholder’s family knows that they will receive value for the business interest rather than being left with shares in a private company that may be difficult to sell.
That sounds relatively simple, but it immediately creates another problem: where do the surviving shareholders find R5 million?
Lif insurance
Going back to our R15 million business, let us assume your husband’s one-third share is worth R5 million. The arrangement could be structured so that the other shareholders have appropriate life policies in place on your husband’s life. If he dies, the policy proceeds provide the surviving shareholders with the funds they need to purchase his shares.
The effect is that the surviving shareholders receive the shares and can continue with the business, while your husband’s estate receives the agreed purchase price.
You are therefore not forced into becoming a shareholder in a business that you have no interest in running, and the surviving partners are not suddenly required to find millions of rand from their own pockets.
Put simply, the agreement determines what happens to the shares, while the life assurance provides the money to make it happen.
Valuing the business
One of the biggest problems with buy-and-sell arrangements is that they are put in place and then forgotten about.
A business may have been worth R6 million ten years ago, with each of three shareholders insured for R2 million. If the business is now worth R15 million, each shareholder’s interest may be worth around R5 million, while the life cover may still only be R2 million.
That leaves a R3 million shortfall and defeats much of the purpose of the arrangement.
The business valuation and the amount of cover should therefore be reviewed regularly to make sure they still match the current value of the business.
The structure is important
Buy-and-sell arrangements can have tax and estate-duty consequences, so they need to be structured correctly. Who owns the policies and who pays the premiums can affect the outcome. The insurance, legal agreements and estate plan should therefore all work together.
If your husband and his partners do not already have a properly structured buy-and-sell arrangement, I would encourage them to deal with it while all three of them are alive and healthy.
I would also encourage the spouses of the shareholders to have at least a basic understanding of the arrangement. You do not need to understand every detail of the business, but you should know what happens if your husband dies, who buys his shares and who the executor should contact.
A buy-and-sell agreement gives the family certainty, protects the remaining shareholders and helps ensure that years spent building a business do not create a financial problem when one owner dies.
KENNY MEIRING IS AN INDEPENDENT FINANCIAL ADVISER
Contact him via phone, email or via contact phone on the financialwellnesscoach.co.za website
Read more of our articles on the Daily Maverick website or newspaper weekly!
 adminfwc
No. 271 – Planning for living and having money left to leave after your death
adminfwc
No. 270 – Making sure that where there is a will, there is clarity, not chaos
adminfwc
No. 269 – Preserving property while treating children fairly
adminfwc
No. 268 – Access bonds can boost emergency savings, but discipline is vital
adminfwc
No. 267 – The case for giving children an early inheritance
adminfwc
No. 266 – Three principles to guide investment decisions
adminfwc
No. 265 – US asset may not be the best bet when it comes to estate planning
adminfwc
No. 264 – Turning property proceeds into a tax-efficient retirement income
adminfwc
No. 263 – How to plan for your pets’ care after your death
adminfwc