
No. 273 – Three effective ways for passing wealth to grandchildren
Question
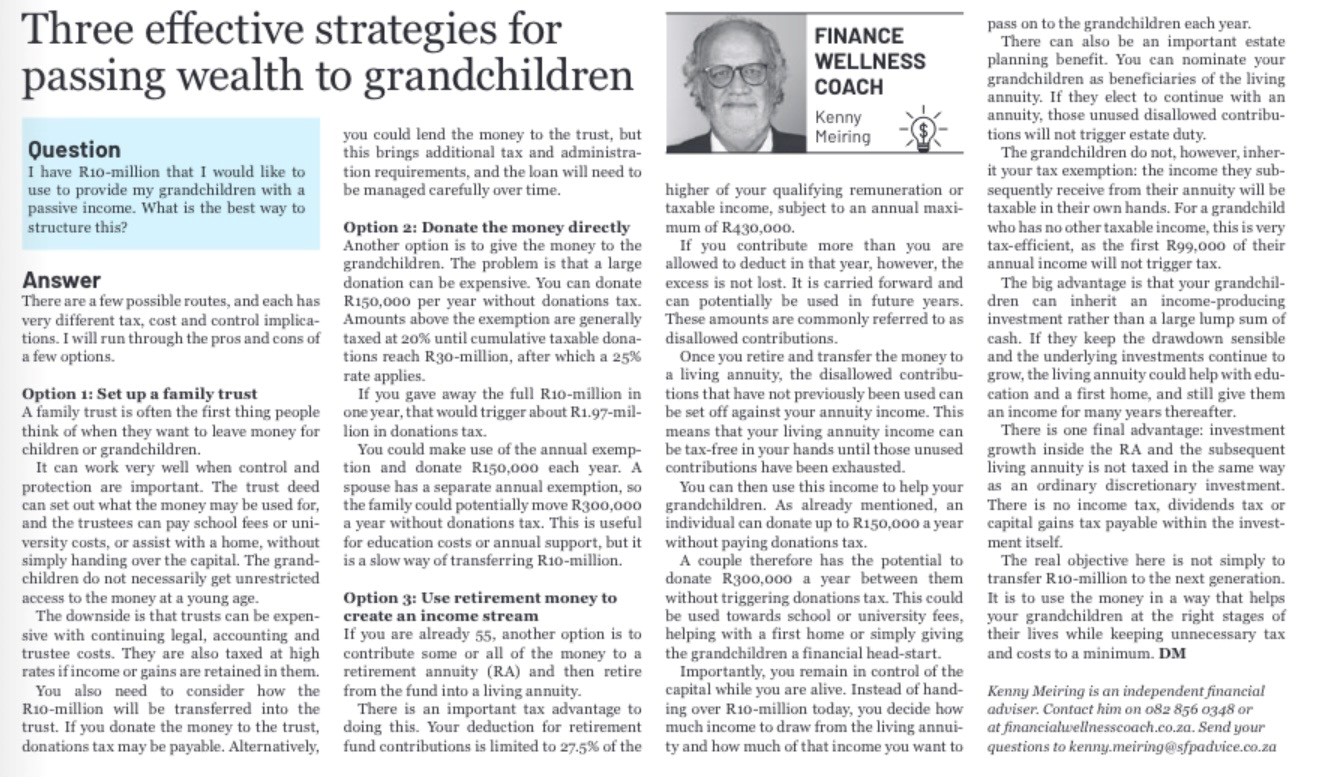
I have R10 million that I would like to use to provide my grandchildren with an ongoing income. What is the best way to structure this?
Answer
There are a few possible routes, and each has very different tax, cost and control implications. I will run through the pros and cons of a couple of options
Option 1: A family trust
A family trust is often the first thing people think of when they want to leave money for children or grandchildren.
It can work very well where control and protection are important. The trust deed can set out what the money may be used for, and the trustees can pay school fees, university costs or assist with a home without simply handing over the capital. The grandchildren do not necessarily get unrestricted access to the money at a young age.
The downside is that a trust can be expensive with ongoing legal, accounting and trustee costs. Trusts are also taxed at high rates if income or gains are retained in the trust.
You also need to consider how the R10 million will actually be transferred into the trust. If you donate the money to the trust, donations tax may be payable. Alternatively, you could lend the money to the trust, but this brings additional tax and administration requirements and the loan will need to be managed carefully over time. So while a trust can provide excellent control and protection, getting the capital into the trust can add another layer of cost and complexity.
Option 2: Donate the money directly
Another option is to give the money to the grandchildren. The problem is that a large donation can be expensive. You may donate R150,000 per year without donations tax. Amounts above the exemption are generally taxed at 20% until cumulative taxable donations reach R30 million, after which a 25% rate applies.
If you gave away the full R10 million in one year that would trigger around R1.97 million in donations tax. That is a very large price to pay simply to move the money from one generation to the next.
You could make use of the annual exemption and donate R150,000 each year. A spouse has a separate annual exemption, so the family could potentially move R300,000 a year without donations tax.
This is useful for education costs or annual support, but it is a slow way of transferring R10 million.
Option 3: Use retirement money to create an income stream
If you are already 55, another option is to contribute some or all of the money to a retirement annuity and then retire from the fund into a living annuity.
There is an important tax advantage to doing this. Your deduction for retirement fund contributions is limited to 27.5% of the higher of your qualifying remuneration or taxable income, subject to an annual maximum of R430,000. If you contribute more than you are allowed to deduct in that year, however, the excess is not lost. It is carried forward and can potentially be used in future years. These amounts are commonly referred to as disallowed contributions.
Once you retire and transfer the money to a living annuity, the disallowed contributions that have not previously been used can effectively be set off against your annuity income. This means that your living-annuity income can be tax-free in your hands until those unused contributions have been exhausted.
You can then use this income to help your grandchildren. Under the current rules, an individual can donate up to R150,000 a year without paying donations tax. A couple therefore has the potential to donate R300,000 a year between them without triggering donations tax. This could be used towards school or university fees, helping with a first home, or simply giving the grandchildren a financial head start.
Importantly, you remain in control of the capital while you are alive. Instead of handing over R10 million today, you decide how much income to draw from the living annuity and how much of that income you want to pass on to the grandchildren each year.
There can also be an important estate-planning benefit. You can nominate your grandchildren as beneficiaries of the living annuity. If they elect to continue with an annuity, those unused disallowed contributions will not trigger estate duty. The grandchildren do not, however, inherit your tax exemption: the income they subsequently receive from their annuity will be taxable in their own hands. For a grandchild who has no other taxable income, this is very tax-efficient as the first R99 000 of their income will not trigger tax
The big advantage is that your grandchildren can inherit an income-producing investment rather than a large lump sum of cash. If they keep the drawdown sensible and the underlying investments continue to grow, the living annuity could help with education and a first home and still provide them with an income for many years thereafter.
There is one final advantage: investment growth inside the retirement annuity and subsequent living annuity is not taxed in the same way as an ordinary discretionary investment. There is no income tax, dividends tax or capital gains tax payable within the investment itself. Combined with the ability to pass the living annuity on to the next generation, this can make it a particularly powerful vehicle for creating a long-term family financial legacy.
The real objective here is not simply to transfer R10 million to the next generation. It is to use the money in a way that helps your grandchildren at the right stages of their lives, while keeping unnecessary tax and costs to a minimum.
KENNY MEIRING IS AN INDEPENDENT FINANCIAL ADVISER
Contact him via phone, email or via contact phone on the financialwellnesscoach.co.za website
Read more of our articles on the Daily Maverick website or newspaper weekly!
 adminfwc
No. 276 – Protecting your family finances while freelancing
adminfwc
No. 275 – Money in the bank could cost you more in tax
adminfwc
No. 274 – Weighing up rental income against long-term investment growth
adminfwc
No. 272 – Plan ahead for business ownership after death
adminfwc
No. 271 – Planning for living and having money left to leave after your death
adminfwc
No. 270 – Making sure that where there is a will, there is clarity, not chaos
adminfwc
No. 269 – Preserving property while treating children fairly
adminfwc
No. 268 – Access bonds can boost emergency savings, but discipline is vital
adminfwc
No. 267 – The case for giving children an early inheritance
adminfwc