
No. 266 – Three principles to guide investment decisions
Question
I inherited R3.8 million and want to invest it sensibly. There is so much talk around costs and types of investment that I am confused. What should I actually look at?
Answer
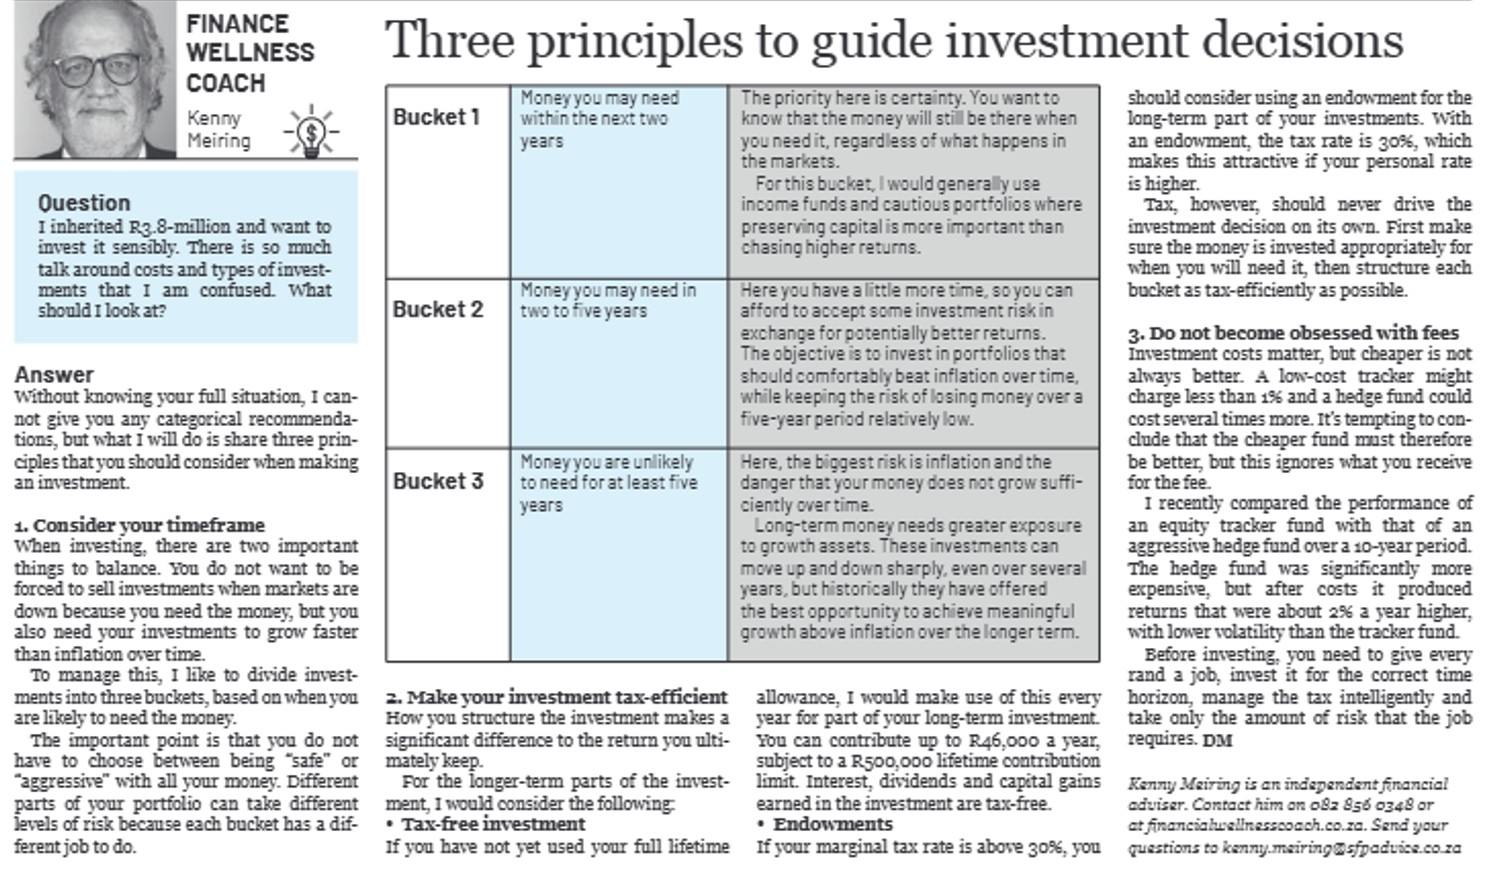
Without knowing your full situation, I cannot give you any categorical recommendations, but what I will do is share 3 principles that you should consider when making an investment.
- Investment Timeframe
When investing, there are two important things to balance. You do not want to be forced to sell investments when markets are down because you need the money, but you also need your investments to grow faster than inflation over time.
To manage this, I like to divide investments into three buckets, based on when you are likely to need the money.
|
Bucket 1 |
Money you may need within the next two years |
The priority here is certainty. You want to know that the money will still be there when you need it, regardless of what happens in the markets.
For this bucket, I would generally use income funds and cautious portfolios, where preserving capital is more important than chasing higher returns |
|
Bucket 2 |
Money you may need in two to five years |
Here you have a little more time, so you can afford to accept some investment risk in exchange for potentially better returns.
The objective is to invest in portfolios that should comfortably beat inflation over time, while keeping the risk of losing money over a five-year period relatively low. |
|
Bucket 3 |
Money you are unlikely to need for at least five years
|
Here, the biggest risk is inflation and the danger that your money does not grow sufficiently over time.
Long-term money therefore needs greater exposure to growth assets. These investments can move up and down quite sharply, even over periods of several years, but historically they have offered the best opportunity to achieve meaningful growth above inflation over the longer term.
|
The important point is that you do not have to choose between being “safe” or “aggressive” with all your money. Different parts of your portfolio can take different levels of risk because each bucket has a different job to do.
- Tax efficiency
How you structure the investment makes a significant difference to the return you ultimately keep. For the longer-term parts of the investment, I would consider the following
Tax-free investment.
If you have not yet used your full lifetime allowance, I would make use of this every year for part of your long-term investment. You can contribute up to R46,000 a year, subject to the R500,000 lifetime contribution limit. Interest, dividends and capital gains earned within the investment are tax-free.
Endowments
If your marginal tax rate is above 30%, then you should consider using an endowment for the long-term part of your investments.
With an endowment, the tax rate is 30% which makes this attractive if your personal rate is higher.
Tax should, however, never drive the investment decision on its own. First make sure the money is invested appropriately for when you will need it; then structure each bucket as tax-efficiently as possible.
- Do not become obsessed with fees
Investment costs matter, but cheaper is not always better.
A low-cost tracker might charge less than 1%, while a hedge fund could cost several times more. It is tempting to conclude that the cheaper fund must therefore be better. But that ignores what you receive for the fee.
I recently compared the performance of an equity tracker fund with that of an aggressive hedge fund over a 10-year period. The hedge fund was significantly more expensive, but after costs it produced returns that were about 2% a year higher, with lower volatility than the tracker fund.
The question is therefore not simply, “What does it cost?” but rather, “What return did I receive after costs, and how much risk did I have to take to achieve it?”
You are not looking for the cheapest investment or the highest return. You are looking for the best return for the level of risk that is appropriate for your timeframe.
Before investing the R3.8 million, I would therefore work through four questions:
- When will I need each part of the money?
- How much investment risk can that particular portion tolerate?
- What tax will the investment generate?
- Am I receiving an appropriate return for the risk and costs I am taking?
You need to give every rand a job, invest it for the correct time horizon, manage the tax intelligently and take only the amount of risk that the job requires.
KENNY MEIRING IS AN INDEPENDENT FINANCIAL ADVISER
Contact him via phone, email or via contact phone on the financialwellnesscoach.co.za website
Read more of our articles on the Daily Maverick website or newspaper weekly!
 adminfwc
No. 276 – Protecting your family finances while freelancing
adminfwc
No. 275 – Money in the bank could cost you more in tax
adminfwc
No. 274 – Weighing up rental income against long-term investment growth
adminfwc
No. 273 – Three effective ways for passing wealth to grandchildren
adminfwc
No. 272 – Plan ahead for business ownership after death
adminfwc
No. 271 – Planning for living and having money left to leave after your death
adminfwc
No. 270 – Making sure that where there is a will, there is clarity, not chaos
adminfwc
No. 269 – Preserving property while treating children fairly
adminfwc
No. 268 – Access bonds can boost emergency savings, but discipline is vital
adminfwc