

No. 236 – Smart moves to make the most of your tax-free investment
Question
I have a tax-free investment at the bank, but the returns seem lower than what my friends are getting from their tax-free investments at an investment company. Can I move my investment or take out another tax-free investment elsewhere?
Answer
Tax-free investments were introduced to encourage South Africans to save over the long term. They offer generous incentives to investors
- No tax on interest
- No tax on dividends
- No capital gains tax (CGT)
- All proceeds can be withdrawn tax-free
Tax-free investments can cause confusion, even among experienced investors. The rules are deceptively simple, but the consequences of misunderstanding them can be expensive — especially if you fall foul of contribution limits or use them for short-term saving.
To get the full benefit of a tax-free investment, you should leave your money invested for as long as possible because the bulk of the benefit comes from the capital gain which is not taxed. The structure is not suited for short-term parking of money, it is specifically geared towards investors being willing to leave their funds untouched for a decade or longer as capital gain needs time to grow.
There are three rules that you must understand:
- Annual contribution limit: R36 000
This limit applies across all your tax-free accounts combined. Not per provider. If you contribute more than R36 000 in a tax year — even accidentally — the excess is taxed at 40%. This is a penalty, not tax.
- Lifetime contribution limit: R500 000
Once you reach this cap, you cannot contribute another cent – ever. This is why you need to be extremely strategic with where you place your tax-free money — because you only get R500 000 of tax free deposits for life.
- You cannot top up what you withdraw
This rule surprises most people. If you put in R36 000, withdraw R10 000 in panic during a market wobble, and then try to “replace” that R10 000, then SARS will say that you have now contributed R46 000 this year. This is because the system records contributions, not net balances.
Because the tax benefit is most powerful over long periods — and because CGT is normally the biggest tax drag on long-term portfolios — it makes sense to use your tax-free allowance for assets with high potential long-term returns like equities.
If the goal is long-term growth over 10, 15, or 20 years, then a well-constructed equity or balanced fund is typically far more appropriate than a cash account at a bank earning 6%. While that may be convenient, it wastes one of the best tax shelters available.
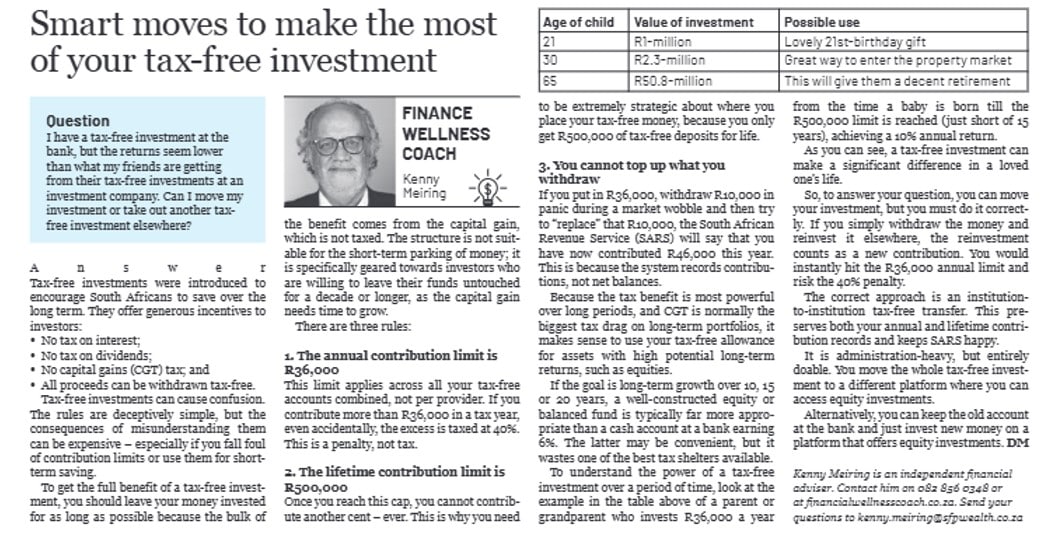
To understand the power of a tax-free investment over a period of time, look at the example below of a parent or grandparent who invests R36 000 a year from the time a baby is born till the R500 000 limit is reached (just short of 15 years), achieving a 10% annual return.
|
Age of child |
Value of investment |
Possible use |
|
21 |
R1m |
Lovely 21st birthday gift |
|
30 |
R2.3m |
Great way to enter the property market |
|
65 |
R50.8m |
This will give them a decent retirement |
As you can see, a tax-free investment can make a significant difference in a loved one’s life.
So, to answer your question, you can move your investment, but you must do it correctly.
If you simply withdraw the money and reinvest it elsewhere, the reinvestment counts as a new contribution. You would instantly hit the R36 000 annual limit and risk the 40% penalty.
The correct approach is an institution-to-institution tax-free transfer. This preserves both your annual and lifetime contribution records and keeps SARS happy. This is admin-heavy, but entirely doable. You move the whole tax-free investment to a different platform where you can access equity investments
Alternatively, you can keep the old account at the bank and just invest new money on a platform that offers equity investments.
KENNY MEIRING IS AN INDEPENDENT FINANCIAL ADVISER
Contact him via phone, email or via contact phone on the financialwellnesscoach.co.za website
Read more of our articles on the Daily Maverick website or newspaper weekly!
 adminfwc
No. 276 – Protecting your family finances while freelancing
adminfwc
No. 275 – Money in the bank could cost you more in tax
adminfwc
No. 274 – Weighing up rental income against long-term investment growth
adminfwc
No. 273 – Three effective ways for passing wealth to grandchildren
adminfwc
No. 272 – Plan ahead for business ownership after death
adminfwc
No. 271 – Planning for living and having money left to leave after your death
adminfwc
No. 270 – Making sure that where there is a will, there is clarity, not chaos
adminfwc
No. 269 – Preserving property while treating children fairly
adminfwc
No. 268 – Access bonds can boost emergency savings, but discipline is vital
adminfwc